インドにおける恒久的施設リスクを回避する方法
Understand permanent establishment risk in India, including the four PE types, treaty day limits, tax rates, the Hyatt ruling, common hiring triggers, and how an EOR can reduce employment-related nexus.
あなたが知っておくべきこと
恒久的施設リスク in India is the risk that your foreign company becomes taxable in India because of what your people or partners do there. You don’t need a registered office for this to happen.
A sales lead who closes deals can do it, and so can an engineer who overstays a treaty limit or a desk your managers quietly control. It rarely looks risky at the time.
The stakes are real. India taxes profits attributed to a PE at a 35% base rate, and PwC’s India tax summary shows the effective rate reaching 38.22% once surcharge and cess apply.
7月2025では、 Supreme Court held that Hyatt International had a fixed place PE in India without owning a single hotel. And since 1 April 2026, every question about a インドにおける恒久的施設 is read under the new Income-tax Act, 2025.
So how do you hire in India without creating a taxable presence? This guide covers the four PE types, treaty day limits, a worked cost example, and the controls that keep your PEリスク low. It also shows where an employer of record services in India helps, and where it doesn’t.
What is Permanent Establishment Risk in India?
Permanent establishment risk is the chance that your activities in India give the Indian tax department the right to tax part of your business profit. A PE is a taxable presence, and once it exists, India can tax the profit attributable to it even if you never set up an Indian entity.
Two layers decide this. Indian law casts a wide net called “business connection”, and your tax treaty with India (the DTAA) then narrows that net through its PE article, which is usually Article 5.
So if someone asks you what a permanent establishment is, the honest answer is “whatever your treaty and the facts say it is”. The label on your contracts matters far less.
How Does Indian Law Define A Permanent Establishment In 2026?
Indian law now defines PE under the Income-tax Act, 2025, which replaced the 1961 Act from 1 April 2026. Section 9 deems income earned through a business connection in India to arise in India.
meaning of permanent establishment official text of the 2025 Act points to section 173(c).
But the old law hasn’t vanished. The Income Tax Department’s transition FAQ confirms that tax years starting before 1 April 2026 still run under the 1961 Act. Hence, a PE audit today can involve both statutes.
Where a treaty applies, you can rely on whichever is more beneficial: the treaty or domestic law. The treaty PE test is usually narrower. That is why your first step is always to read your own treaty, line by line, before you sign a single offer letter in India.
How Is A PE Different From A Business Connection Or Significant Economic Presence?
A PE is the treaty test. A business connection is the domestic test, and significant economic presence (SEP) is a digital nexus rule that sits inside that domestic test.
| ホイール試乗 | Legal source | Physical presence needed? | 典型的なトリガー |
|---|---|---|---|
| ビジネスコネクション | Section 9, Income-tax Act, 2025 | 常にではない | Dependent agent, stock of goods, operations in India |
| Significant economic presence | Section 9 and the notified rules | いいえ | ₹2 crore of transactions or 3 lakh Indian users |
| 恒久的施設 | DTAA Article 5; section 173(c) | 通常ははい | Fixed place, agent, services, construction |
SEP applies when a non-resident’s transactions with people in India cross ₹2 crore in a year, or when it deals systematically with 3 lakh or more Indian users. EY reported these thresholds when India notified them in May 2021.
That said, SEP is absent from most treaties. If you can claim treaty benefits, the treaty PE article generally decides the outcome.
What Are The Four Types Of Permanent Establishment In India?
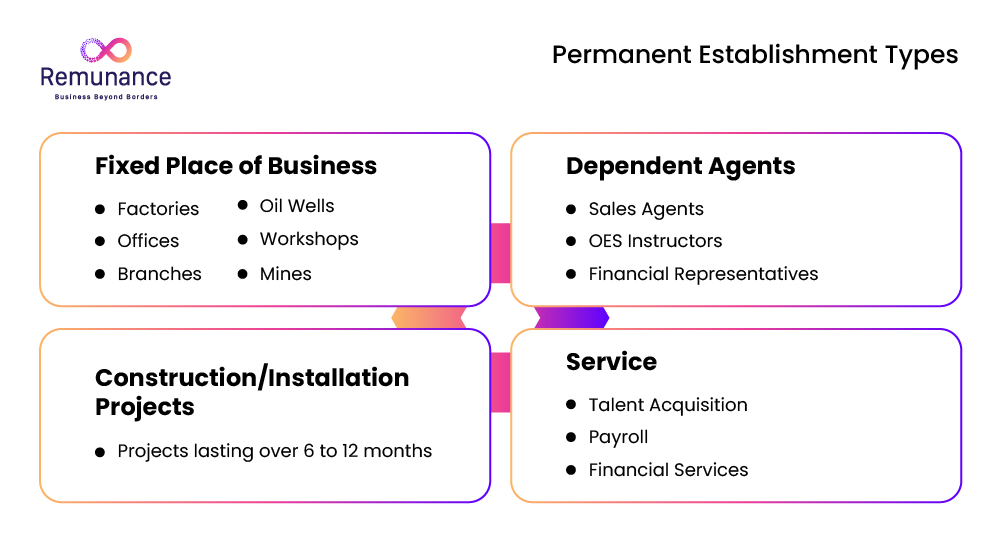
The four types are fixed place PE, dependent agent PE, service PE and construction PE. Each has its own trigger. So one company can be safe on three and exposed on the fourth.
| PEタイプ | 何がきっかけとなるのか | Time test | Common hiring example |
|---|---|---|---|
| 固定された場所 | A place of business at your disposal | Some permanence; no single day count | Desk leased in your name, or a site you control |
| Dependent agent | A person who habitually concludes contracts, or plays the principal role, for you | なし | India sales head with deal authority |
| サービス | Your employees or personnel furnishing services in India | Treaty-specific, e.g., over 90 days in 12 months (India-US) | Engineers or consultants on long India visits |
| 構築 | Building site, installation or assembly project | Treaty-specific, often 6 to 12 months | Plant installation or commissioning supervision |
When Does A Fixed Place PE Arise?
A fixed place PE arises when a place in India is at your disposal and your business runs through it. Ownership doesn’t decide it. Control does. That single idea explains most fixed place disputes you will read about in India.
That is the lesson of Hyatt International Southwest Asia, decided by the Supreme Court on 24 July 2025. Hyatt, a UAE company, only provided strategic oversight to Indian hotels that another company owned, yet the court still found a fixed place PE under the India-UAE treaty.
SCC Online’s case summary notes the court weighed the right of disposal, the degree of control and operational authority. Hyatt argued its staff never crossed the treaty’s nine-month service limit. The court held the fixed place test runs independently of that limit.
Let’s say your India team works from a co-working space leased in your company’s name. Or your managers direct daily work at a vendor’s premises. Both facts point to a place at your disposal. If your team needs a base, plan office space for an EOR team through the EOR, not in your own name.
Purely preparatory or auxiliary work, such as storage or information gathering, is usually carved out. But the carve-out is narrow and depends on facts.
When Does A Dependent Agent PE Arise?
A dependent agent PE arises when someone in India habitually concludes contracts for you. It also arises when they habitually play the principal role leading to contracts you sign without material changes.
That second limb comes from Article 12 of the OECD Multilateral Instrument. India aligned its domestic business connection rule with this wording through the Finance Act, 2018.
This is the PE type foreign companies trigger most often by accident. Nobody plans it.
Suppose you hire a country sales manager in Bengaluru. She negotiates price and agrees terms. Your US head office then signs the contract as it stands.
On paper, she has no signing authority. In substance, she plays the principal role.
The MLI wording applies only where both treaty partners adopted that article. The US never signed the MLI, so the India-US treaty keeps its original agent clause. Building a remote sales team in India? Scope the roles before you hire.
When Does A Service PE Arise?
A service PE arises when your employees or other personnel furnish services in India beyond your treaty’s time limit. The limit differs by country, and some treaties apply a much tighter rule when the work is done for a group company.
| 条約 | Standard service PE limit | Related-party rule |
|---|---|---|
| インド-米国 | More than 90 days in any 12-month period | Services for a related enterprise fall in scope with no day test |
| インド-シンガポール | More than 90 days in a fiscal year | More than 30 days for related enterprises |
| インド-UAE | Nine months in a 12-month period (as argued in Hyatt) | Check the treaty text |
The India-US clause is the one US companies misread most. Read it twice. Under Article 5(2)(l), services performed in India for a related enterprise sit inside the service PE rule without the 90-day test. So even a short visit to support your own Indian affiliate needs a tax check first.
Physical presence still counts. In a ruling summarised by BDO India, the Delhi tribunal rejected a “virtual” service PE and counted only the days when staff were physically present in India.
Secondments are the classic trap. In its 2007 Morgan Stanley ruling, the Supreme Court held that staff deputed to work for an Indian affiliate could create a service PE, while visits made purely to protect the parent’s own interests did not.
2023年XNUMX月、 draft order attributed about ₹55 crore of income to Netflix’s Indian PE. Reports cited seconded staff and infrastructure as the basis. If you move people across borders, read how an EOR supports expat employees in India.
When Does A Construction PE Arise?
A construction PE arises when a building site, installation or assembly project in India lasts longer than your treaty allows. Many Indian treaties set 6 to 12 months. The India-US treaty uses a shorter 120-day test.
Supervisory work connected to the project can count too, so track engineer visits on installation jobs as closely as you track the project timeline itself.
What Does A PE Cost A Foreign Company In India?
A PE costs you Indian corporate tax on the attributed profit, plus the burden of being an Indian taxpayer. The permanent establishment tax alone can take close to 38% of the profit India attributes to you.
What Tax Rate Applies To Profits Attributed To A PE?
Profits attributed to a PE face a 35% base rate, cut from 40% by the Finance Act, 2024. A surcharge and a 4% health and education cess sit on top.
| Attributed profit | 基準率 | サーチャージ | セス | 実効レート |
|---|---|---|---|---|
| 最大1億ルピー | 35% | 皆無 | 4% | 36.40% |
| 1億ルピーから10億ルピー | 35% | 2% | 4% | 37.13% |
| Above ₹10 crore | 35% | 5% | 4% | 38.22% |
Compare that with an Indian subsidiary under the concessional regime, which pays about 25.17%. The gap is why a growing India team eventually changes the maths.
What Does A Worked PE Cost Example Look Like?
Here is an illustrative case. The margin is our assumption, not a statutory figure.
Let’s say a US SaaS company employs a sales lead in India who plays the principal role in closing ₹8 crore of contracts a year. The tax officer treats her as a dependent agent PE and attributes a 15% profit margin to India.
| 手順 | 計算 | 結果 |
|---|---|---|
| Attributed profit | ₹8 crore × 15% | 1.2億ルピー |
| Effective rate (₹1 crore to ₹10 crore band) | 35% × 1.02 × 1.04 | 37.128% |
| Indian tax per year | ₹1.2 crore × 37.128% | 44.55万ルピー |
That figure excludes interest and any penalty. It also assumes your home country gives full credit for the Indian tax, which isn’t guaranteed when the two countries disagree on how much profit belongs to India.
What Else Follows Once A PE Is Found?
Once a PE is found, you become an Indian taxpayer for that profit. The follow-on compliance work often costs more management time than the tax itself.
-
- You file an Indian income tax return and keep books that support the profit attribution.
- You prepare transfer pricing records for dealings between the PE and your head office.
- You face withholding obligations on certain payments.
- Officers often test several years at once.
- You may carry double tax while treaty relief is negotiated.
For the wider picture, read our guide on the tax implications of using an employer of record.
報酬支払元雇用主
Want To Reduce Permanent Establishment Tax Risk In India?
Understand your potential PE exposure, tax costs, and compliance obligations before hiring or expanding your India operations.
Assess Your India PE Risk
Which Everyday Hiring Decisions Create PE Risk?
Four decisions create most PE risk. They are who can commit you to contracts, who travels to India, whose premises your people use and how you engage contractors.
| Role in India | PE type exposed | リスクレベル | メインコントロール |
|---|---|---|---|
| Software engineer on your product | Rarely any | ロー | Keep work internal; no customer authority |
| カスタマーサクセスまたはサポート | Service (if foreign staff visit) | 低〜中 | Track visitor days |
| Sales development rep booking meetings | Dependent agent | 技法 | No pricing or terms authority |
| Country manager or sales head | Dependent agent, possibly fixed place | ハイ | Written authority limits; real head office approval |
| Seconded expat from head office | サービス | ハイ | Treaty day count; secondment agreement |
| Exclusive long-term contractor | Dependent agent, plus misclassification | 中から高 | Genuine independence; multiple clients |
Can A Single Remote Employee In India Create A PE?
Yes. One employee can create a PE if the role carries contract authority, or if you control the place they work from. A developer writing internal code from home rarely does. A senior hire who negotiates customer deals often does.
Home offices? Grey area. The question is whether the space is at your disposal. Suppose you require it, pay for it or print it as a business address. Each of those facts pushes the answer towards yes.
Do Independent Contractors Reduce Or Increase PE Risk?
Contractors don’t automatically reduce PE risk. An exclusive, long-term contractor who works only for you can look like a dependent agent. Or a disguised employee. Sometimes both.
That second risk grew sharper once India’s four labor codes took effect on 21 November 2025. Read our guide on 従業員の誤分類比較する contractor of record vs employer of record 選択する前に。
How Can You Avoid Permanent Establishment Risk In India?
You avoid PE risk by controlling what your India team may do, where they do it, and how long foreign staff stay. These eight steps cover most cases.
-
- Read your treaty first: Pull Article 5 of your DTAA with India and note the service and construction limits.
- Map every India role: List who negotiates, who signs, who visits, and who manages premises.
- Cap contract authority in writing: Keep pricing, terms, and final acceptance with head office, and make that approval real.
- Track visitor days: Log each foreign employee’s service days in India, with related-entity work counted separately.
- Avoid premises at your disposal: Don’t lease space in your own name or direct work from a partner’s site without planning for a PE.
- Engage contractors as genuine independents: Allow other clients, output-based scopes and their own tools.
- Price intra-group services at arm’s length: Document fees so the setup survives a transfer pricing review.
- Review yearly and after every change: New roles, promotions and bigger deals change the answer.
現場の声を力強いメッセージへ。 EORコンプライアンスチェックリスト turns the employment side of this into a monthly routine.
What Should Your Contracts And Policies Say?
Your contracts should state who holds authority and how decisions flow. Words alone won’t protect you. Tax officers read emails, CRM notes, and approval logs, so your paper trail has to tell exactly the same story as your contracts.
-
- A job description with no power to bind the company and no role in agreeing price or terms.
- A deal approval matrix where head office accepts or amends every offer.
- Titles and email signatures that avoid “authorized signatory”.
- A travel policy that needs tax sign-off before India trips.
- A scope clause in your 記録上の雇用主契約 that limits duties to the agreed role.
How Do You Track Service PE Days Properly?
Track days of service delivered in India, per treaty year, per entity served. A shared calendar isn’t enough.
Suppose your Singapore company sends two engineers to its Indian affiliate on different dates, for 16 days each. That makes 32 service days. It crosses the 30-day related-party limit under the India-Singapore treaty.
Log arrival, departure, work location, entity served, and type of service. Keep boarding passes and timesheets. Then prove it. When an officer asks for the count, you want records, not recollections.
Does An Employer Of Record Remove PE Risk In India?
An employer of record removes the risk of employing people in India directly. It does not remove PE risk created by what those people do. That distinction is the honest answer to the employer of record permanent establishment 質問。
With an EOR, the Indian entity is the legal employer. It runs payroll, TDS, PF, ESI, and labor code compliance. You don’t register as an Indian employer, and you can start operating in India without entity formation. That removes a major nexus.
But suppose your EOR-employed sales head closes deals for you. The dependent agent test looks at what she does, not at whose payroll she sits on, so that risk stays with you. Same with premises. If you control the place she works from, the fixed place test still applies.
What Does An EOR Take Off Your Plate?
An EOR takes over employment, payroll, and statutory compliance, so your company isn’t the Indian employer.
-
- Employment contracts under Indian law and the four インドの労働法.
- Monthly payroll, TDS and statutory filings.
- PF, ESI, gratuity and leave administration.
- Onboarding, exits and records.
- A documented service fee, with zero-rated GST on EOR services where the conditions are met.
Where Does an EOR Not Protect You?
An EOR doesn’t protect you when the risk comes from conduct, premises or travel.
-
- EOR staff who negotiate and close your contracts.
- Offices or desks you lease or control.
- Your own foreign employees visiting India beyond treaty limits.
- A structure where your company is, in substance, run from India.
That last point touches on the place of effective management (POEM). If key management decisions for your company are really taken in India, the company itself can be treated as Indian resident. We cover these limits openly in when an EOR is not the right option.
When Should You Move From EOR To A Subsidiary?
Move to a subsidiary when your India team sells to Indian customers, signs local contracts or grows into a leadership centre. By then a PE is likely anyway. And the maths flips, because a subsidiary taxed at about 25.17% costs less than PE profits taxed at up to 38.22%.
Run the numbers in our EOR vs entity cost comparison。 次に読んでください EORか子会社か:どちらを選ぶべきか と私たちのガイド how to set up a subsidiary in India.
Many firms also build a GCC in India through the EOR model first, then transfer it into an entity later.
How Does Remunance Help You Keep PE Risk In Check?
Remunance is a Pune-based employer of record that hires, pays, and manages your India team without an Indian entity. Our CEO, Ranjana Vaidya, FCA, reviewed this guide.
-
- We hire your people on Indian contracts that follow the four labor codes.
- We help you write role scopes that keep contract authority with your head office.
- We run payroll, TDS, PF, ESI and statutory filings every month.
- We document the EOR service fee for your tax and transfer pricing files.
- We plan your move to a subsidiary when your India presence outgrows EOR.
PE conclusions depend on your treaty and your facts. So we work alongside your tax adviser, not in place of one.
Want a quick read on your exposure? Book a PE-safe hiring call with our India team. You can also price your team with our インド向けEORコスト計算ツール.
報酬支払元雇用主
Keep Your India Hiring PE Risk In Check
Hire and manage your India team through Remunance while keeping contracts, payroll and compliance structured. Work with our India team alongside your tax adviser.
Talk To Our India EOR Team よくある質問(FAQ)
What Is Permanent Establishment In India In Simple Terms?
A permanent establishment is a taxable presence of a foreign company in India. It can be a fixed place, a dependent agent, services delivered by your staff in India or a long construction project. Once it exists, India can tax the profit linked to it.
How Many Days Can A Foreign Employee Work In India Without Creating A PE?
It depends on your treaty. Under the India-US treaty, services over 90 days in any 12-month period can create a PE. Services for a related enterprise have no day test at all. Under the India-Singapore treaty, the limit is 90 days, or 30 days for related enterprises.
Can One Remote Employee In India Create A PE?
Yes, if that person habitually concludes contracts for you, plays the principal role in closing them or works from a place you control. A remote employee doing internal work, with no customer authority, rarely creates one.
Can An Employer Of Record Eliminate Permanent Establishment Risk?
No. An EOR removes the employment link and handles payroll and compliance. PE risk from contract authority, premises you control or foreign staff visits still depends on how you run the role.
What Tax Rate Applies To A PE In India?
Profits attributed to a PE are taxed at a 35% base rate. With surcharge and 4% cess, the effective rate ranges from 36.40% to 38.22%, depending on the attributed profit.
What Changed For PE Under The Income-Tax Act, 2025?
The 2025 Act replaced the 1961 Act from 1 April 2026. Business connection now sits in section 9, and PE is defined through section 173(c). Tax years that began before 1 April 2026 still follow the 1961 Act.
What Did The Supreme Court Decide In The Hyatt Case?
On 24 July 2025, the Supreme Court held that Hyatt International Southwest Asia had a fixed place PE in India under the India-UAE treaty. Its control over Indian hotel operations was enough, even without owning the premises.
Is Significant Economic Presence The Same As A PE?
No. SEP is a domestic-law nexus that applies above ₹2 crore of transactions or 3 lakh Indian users. A PE is a treaty concept. If you can claim treaty benefits, the treaty PE test usually prevails.
Disclaimer: This guide is for general information and reflects the law as of 15 September 2026. It is not tax or legal advice. Please take advice on your specific treaty and facts before acting.
関連記事
インドの雇用者記録制度(2026年):法人を持たずに従業員を雇用する

EORコンプライアンスチェックリスト:採用前に知っておくべきこと

インドにおける雇用者記録上の税務上の影響:グローバル企業のための完全ガイド(2026年版)
EOR(強化石油回収)か子会社か:グローバル展開にはどちらを選ぶべきか?